Humana’s Medicare Advantage Exits Will Affect About 600,000 Members in 2027, Who Get a Special Enrollment Window From Dec. 8 Through February
Somewhere in a kitchen-table stack of Medicare mail this month sits a letter that matters more than the rest: a notice from Humana saying a member’s Medicare Advantage plan will not be back in 2027. Humana has said its plan exits for next year will affect about 600,000 members, and federal rules gave those members a special window to choose new coverage that runs from Dec. 8 through the end of February.
The insurer has not published a list of the plans, counties or states involved. That means the letter itself is the clearest signal a member is affected, and the dates in it set the clock.
How Many Humana Members Are Losing Their Plan
Humana disclosed the cuts on its second-quarter earnings call on July 29. According to Healthcare Dive’s report on the call, the exits are expected to affect roughly 600,000 seniors, about 8% of the company’s 7.2 million Medicare Advantage members.
Chief Financial Officer Celeste Mellet said the company aims to “remove or cut off the lower tail of profitability and returns,” and that the exits “should not be viewed primarily as a response to the plans’ star ratings,” according to Healthcare Finance News. The same report said most of the discontinued plans carry 2027 star ratings of 3.5 or lower, and that federal rules required nonrenewal notices for contracts ending Dec. 31 to be dated Oct. 2.
Humana expects to keep a share of those members in its other plans. Healthcare Dive reported the company expects to bring back about 40% of affected members, roughly 240,000 people. The rest would need a plan from another insurer or would land in Original Medicare.
Humana is not leaving Medicare Advantage. On Oct. 2, the company said its 2027 plans will be sold in about 2,600 counties across 45 states and Washington, D.C., Healthcare Finance News reported, down from 46 states this year. So a member whose specific plan is ending may still find another Humana plan in the same county.
The Two Windows on the Calendar
Members with a nonrenewal letter actually have two chances to pick new coverage.
The first is Medicare’s regular open enrollment, which runs Oct. 15 through Dec. 7. A plan chosen during that period starts Jan. 1, so there is no gap.
The second is the special enrollment period for people whose plan is not being renewed. Medicare.gov says that window runs “between December 8 and the last day in February of the following year,” and lets members switch to another Medicare Advantage plan, a Medicare drug plan or a Medicare Cost Plan. For this round of exits, that means Dec. 8, 2026 through Feb. 28, 2027.
The health policy group KFF adds a third option for later in the year: the Medicare Advantage open enrollment period from Jan. 1 to March 31, when people already in a Medicare Advantage plan can switch once.
What Happens to Members Who Do Nothing
A member who never picks a new plan does not lose Medicare. Medicare.gov says anyone who does not join another Medicare Advantage plan before the old one ends is enrolled in Original Medicare.
The catch is drug coverage. KFF notes that people without Extra Help or drug coverage from another source, such as the VA or a former employer, need to choose a standalone Part D plan to have Medicare drug coverage. The Maryland Insurance Administration warns that someone who returns to Original Medicare without a Part D plan may pay the full cost of prescriptions.
Members who move to Original Medicare often add a Medigap supplement policy to help with the costs Original Medicare leaves to the patient. That is where the nonrenewal letter brings a second protection.
The Medigap Right That Comes With the Letter
Normally, an insurer can review a person’s health before selling a Medigap supplement policy, and can charge more or say no. A plan exit changes that.
Indiana’s State Health Insurance Assistance Program explains in its guide to Medigap rights that when a Medicare Advantage plan leaves Medicare or stops serving an area, the member can return to Original Medicare and buy certain Medigap policies without the usual medical screening. The window opens as early as 60 days before the old coverage ends and closes 63 days after. Maryland’s advisory says insurers cannot deny those applicants or price the policy based on health conditions during that window.
Because the old plan ends Dec. 31, the 63-day clock runs into early March. Applying before Jan. 1 lets the Medigap policy start the same day the Advantage plan stops.
State rules can add protections on top of the federal ones, so the state insurance department or local SHIP counselor is the place to confirm what applies. Anyone weighing a standalone drug plan will also want to know that the Part D out-of-pocket cap rises to $2,400 in 2027 and that the standard Part D deductible climbs to $700.
What Members Can Do This Week
The letter dated Oct. 2 should name the plan that is ending. With it in hand, a member can compare 2027 plans on Medicare.gov’s plan finder or by calling 1-800-MEDICARE, checking that their doctors and prescriptions are covered.
Those comparing replacement Advantage plans can also check the projected average 2027 Medicare Advantage premium. Choosing before Dec. 7 avoids any lapse. Waiting until the special window is allowed, but anyone who wants Medigap and a drug plan instead of another Advantage plan has the most room by starting early, while both the Medigap protection and the enrollment periods are open.
Get stories like this by email. Sign up for The Parent Diaries Letter.
This article was produced with AI assistance and edited for accuracy against the sources linked above.
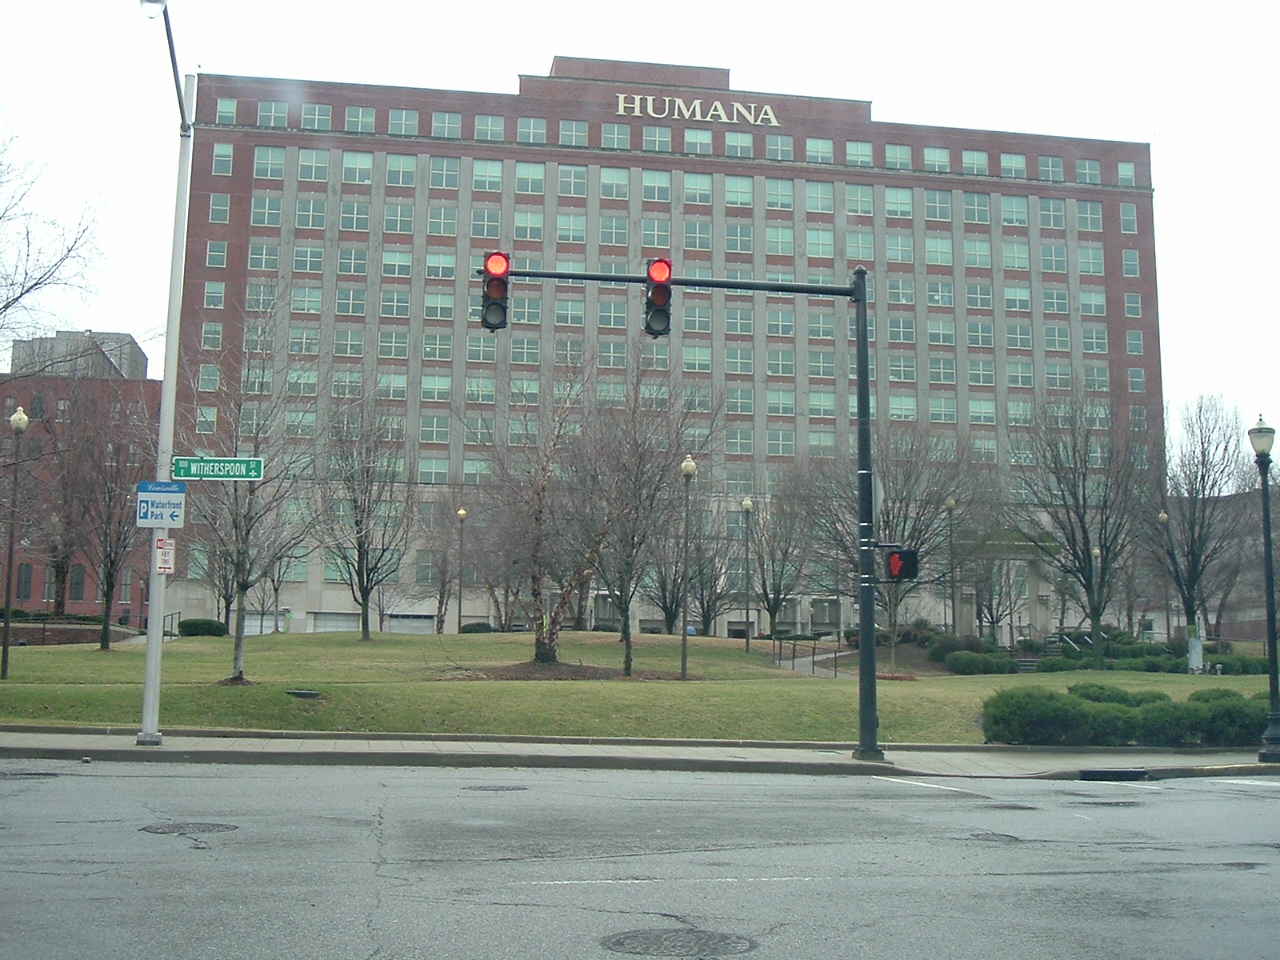
Image: Angry Aspie – CC BY 3.0/Wikimedia Commons