Single Seniors 65 and Older Can Deduct Up to $24,150 on Their 2026 Taxes, Including a New $6,000 Bonus
A retiree filing alone next spring can shield a lot more income from federal tax than a younger single filer. For tax year 2026, a single taxpayer who is 65 or older can deduct as much as $24,150 before any income tax is figured, as long as their income stays under the limit for the new senior deduction.
That total is three separate breaks stacked together: the regular standard deduction every filer gets, the extra amount the tax code has long given people 65 and older, and a new bonus deduction of up to $6,000 that runs from 2025 through 2028. Each piece works a little differently, and only one of them shrinks at higher incomes.
How the $24,150 adds up
For 2026 returns, which are filed in early 2027, the three pieces for a single filer age 65 or older are:
- Standard deduction: $16,100 for single filers
- Extra deduction for age 65 and older: $2,050, up from $2,000 for 2025
- New senior bonus deduction: up to $6,000
Put together, that is a possible deduction of $24,150, according to a 2026 breakdown of the age-65 deductions. The new bonus stacks on top of the long-standing age-65 add-on, which is $2,050 for single filers and heads of household and $1,650 for each qualifying spouse on a joint return in 2026, a guide with worked examples notes.
In practical terms, a single retiree whose only taxable income is $24,000 in pension and IRA withdrawals would owe no federal income tax on it for 2026. Every dollar of that income falls under the deduction.
Who qualifies for the $6,000 bonus
The new deduction comes from the tax law Congress passed in July 2025. To claim it, a taxpayer must be 65 or older by the last day of the tax year, so anyone who turns 65 on or before Dec. 31, 2026, counts for 2026. The return also has to include a valid Social Security number for each person claiming it, according to the IRS fact sheet on the deduction.
Unlike the regular extra deduction for age 65, the bonus does not require taking the standard deduction. The IRS says it is available to both itemizers and non-itemizers. A retiree who itemizes mortgage interest, medical costs or charitable gifts can still subtract the $6,000 on top.
Married couples get it per person. When both spouses are 65 or older, a joint return can claim up to $12,000. When only one spouse is 65 or older, the couple claims a single $6,000, one adviser’s guide to the 2026 deduction explains. Married people must file jointly to get any of it, and for couples the phaseout starts at $150,000 of income.
Where the deduction starts to shrink
The full $6,000 is for single filers with modified adjusted gross income of $75,000 or less. Above that, it drops by 6 cents for every dollar of extra income, and it disappears entirely at $175,000.
A worked example from a tax guide on the senior deduction shows how the math goes. A single filer with $100,000 of modified adjusted gross income is $25,000 over the line. Six percent of $25,000 is $1,500, so that person’s bonus deduction falls to $4,500.
Some other points along the way, using the same 6% rule:
- $75,000 or less: full $6,000
- $100,000: $4,500
- $125,000: $3,000
- $150,000: $1,500
- $175,000 or more: nothing
The regular $2,050 extra deduction for age 65 has no income limit, so higher-income seniors keep that piece even when the bonus is gone.
What counts toward the income limit
Modified adjusted gross income for this deduction starts with adjusted gross income, the figure near the bottom of the first page of Form 1040. For many retirees, that includes pension income, traditional IRA and 401(k) withdrawals, required minimum distributions, interest, dividends and wages from any part-time work.
Social Security counts only to the extent it is taxable. The new deduction does not make Social Security tax-free. It lowers overall taxable income, which can reduce the tax owed on the portion of benefits that is taxable, as Yahoo Finance explained in its look at the deduction.
Retirees close to the $75,000 line may be able to keep more of the bonus by planning withdrawals. A large IRA distribution or a one-time capital gain late in the year can push income over the limit and cut the deduction.
How it is claimed, and for how long
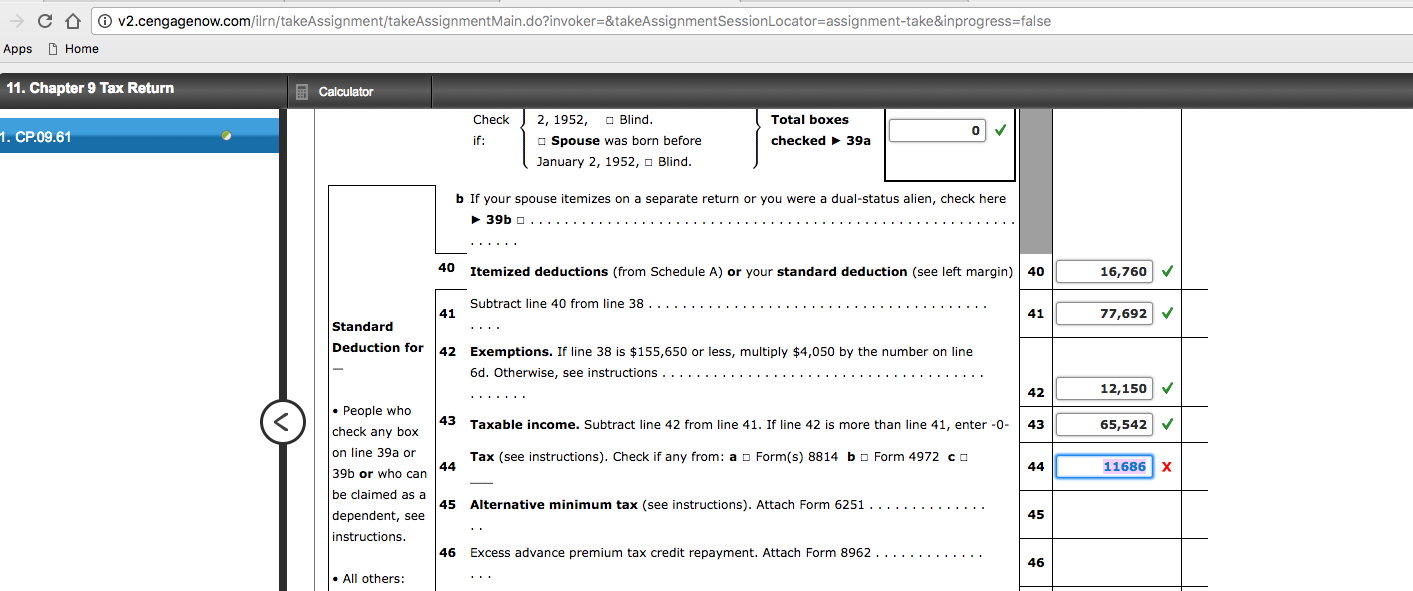
The bonus is claimed on a new form, Schedule 1-A, filed with Form 1040 or Form 1040-SR, the version written for taxpayers 65 and older. Tax software and paid preparers add it for filers whose age and income qualify, and retirees preparing their own returns can confirm the Schedule 1-A line appears before filing.
The deduction is temporary. Under current law it applies to tax years 2025 through 2028, so 2026 returns are the second of four years retirees can claim it. The regular standard deduction and the extra $2,050 for age 65 are permanent parts of the tax code and adjust for inflation each year.
For a single retiree under the income limit, that adds up to a lot of money kept out of the tax calculation. At the 12% federal bracket, the $6,000 bonus alone is worth about $720 in tax saved, and at the 22% bracket about $1,320.
This article was produced with AI assistance and edited for accuracy against the sources linked above.
Image: Plinskarch – CC BY-SA 4.0/Wikimedia Commons