Couples Earning Up to $200,000 Can Deduct Interest on a Car Loan Next Tax Season, but Only for Vehicles Assembled in the U.S.
A new car payment is one of the biggest monthly bills many households carry, and in the first years of a loan most of each payment is interest. Under the 2025 tax law, a share of that interest can now come off federal taxable income, but only if the car meets a test most buyers never thought about at the dealership: where it was put together.
The Internal Revenue Service’s Working Families Tax Cuts page says the deduction is worth up to $10,000 a year for tax years 2025 through 2028. It phases out above modified adjusted gross income of $100,000 for single filers and $200,000 for married couples filing jointly, and the vehicle must have undergone final assembly in the United States.
Which Loans and Vehicles Qualify
The loan has to be new. The IRS says the deduction applies to interest on loans originated after Dec. 31, 2024, used to buy a vehicle for personal use and secured by a lien on that vehicle. A loan from 2023 or 2024 does not qualify, even if payments continue into 2026.
The vehicle must be a car, minivan, van, SUV, pickup truck or motorcycle with a gross vehicle weight rating under 14,000 pounds. Lease payments do not count. Interest on a qualifying loan that is later refinanced is generally still eligible, the IRS says.
Unlike many tax breaks, this one does not require itemizing. The IRS says it is available to both itemizers and people who take the standard deduction.
The Assembly Test
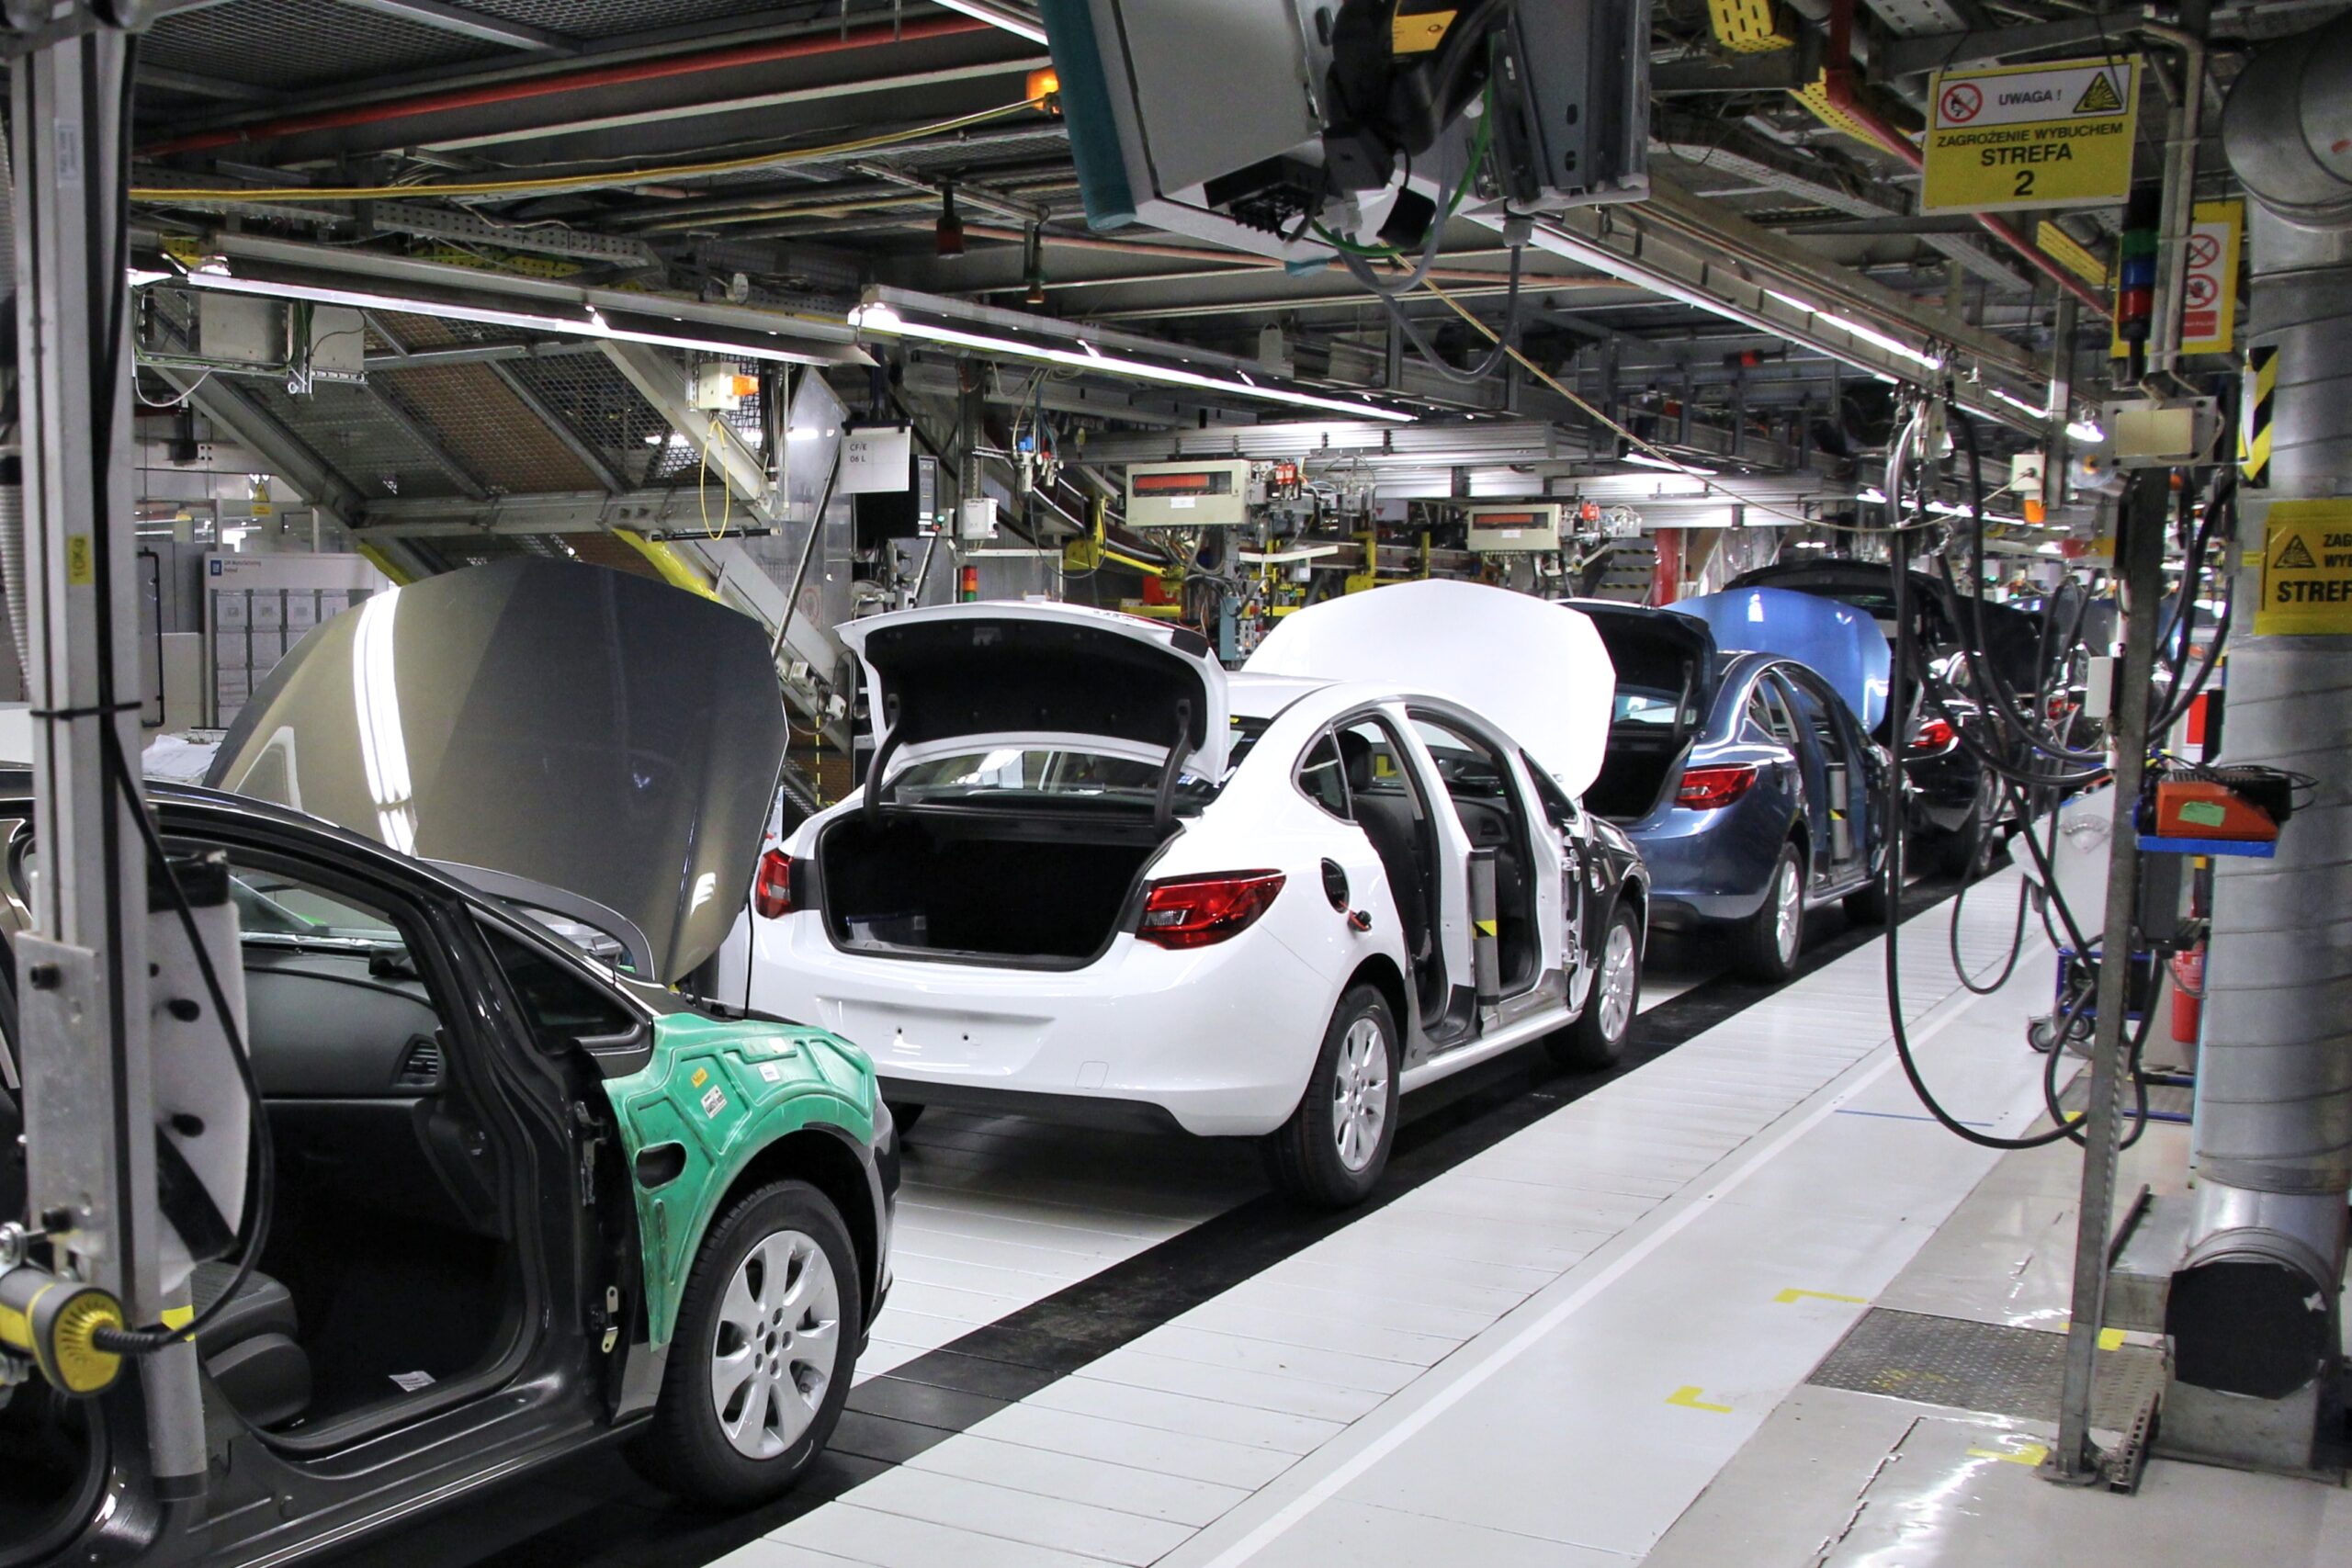
The final assembly rule is the one that rules out the most cars. A vehicle sold by an American brand can be built in Mexico or Canada, and a vehicle sold by a foreign brand can be built in Tennessee, Alabama or South Carolina. The brand on the grille does not decide it. The location of final assembly does.
The IRS says buyers can confirm final assembly three ways: from the vehicle identification number, from the label posted on the vehicle at the dealer, or with the National Highway Traffic Safety Administration’s VIN decoder, which reports where a vehicle was manufactured.
The VIN also has to go on the tax return. The IRS says the vehicle identification number must be included for each year the deduction is claimed. The Tonic Edit looked at the assembly rule in detail in its story on vehicles built overseas.
Where the Income Limits Fall
The $10,000 figure is the most a household can deduct in a year, regardless of how much interest it paid. The income limits decide whether a household gets the full amount. A single filer with modified adjusted gross income of $100,000 or less, or a married couple filing jointly at $200,000 or less, can take the full deduction. Above those levels, the deduction shrinks.
Few car loans generate $10,000 of interest in a single year, so the cap matters less than the income limit for most buyers. A household paying a few thousand dollars of interest a year can deduct all of it if the vehicle and loan qualify and income is under the line.
A deduction lowers taxable income rather than the tax bill directly. A married couple in the 12% bracket who deducts $3,000 of car loan interest saves about $360 in federal income tax. In the 22% bracket, the same $3,000 saves about $660.
What Lenders Will Send
The law also put a new reporting duty on lenders. The IRS says lenders must file information returns and give borrowers statements showing the interest they received, so borrowers will have a document showing the figure to claim.
The IRS named the car loan deduction in its Nov. 16 reminder for the 2027 filing season as one of the new provisions on 2026 returns, along with deductions for tips, overtime and seniors. The agency said it is still releasing information on these provisions and pointed taxpayers to its Working Families Tax Cuts page for updates.
The deduction comes from Public Law 119-21, signed July 4, 2025, according to the GovInfo record of the law. The IRS summarizes the law’s main provisions for individuals on its provisions page.
What Car Buyers Can Check Now
For anyone who financed a vehicle in 2025 or 2026, three checks settle most questions before tax season. First, the loan date: it must be after Dec. 31, 2024. Second, the assembly location: the VIN or the window label will show it. Third, the use: the vehicle must be for personal use, not a lease and not a heavy commercial truck.
A married couple earning under $200,000 who bought a U.S.-assembled SUV with a 2026 loan, for example, can deduct every dollar of interest paid this year, up to $10,000, on the return they file next spring.
This article was produced with AI assistance and edited for accuracy against the sources linked above.