A Retired Boomer Realized Her Grown Children Might Expect an Inheritance, but She and Her Husband Plan to Spend Their Savings, and the Advice Wasn’t to Make a Dramatic Confession
A lighthearted conversation about family inheritance left a retired couple wondering whether their adult children understood what the future might hold. In a reader letter published in Business Insider’s For Love & Money column, a woman in her 60s described how her children joked about which sibling was the favorite and who would eventually inherit the family’s wealth. The conversation sounded playful at the time, so she and her husband saw no reason to correct their assumptions.
Away from that dinner table, however, the couple had been making very different plans for their later years. Rather than preserving their savings for the next generation, they intended to use their money to enjoy retirement and cover their future needs. Their question was not whether they could afford to leave a fortune behind, but whether they needed to tell their children that a substantial inheritance might never materialize.
The Couple Had Reached Retirement After Decades of Work
The letter writer described herself and her husband as members of the baby boomer generation who had worked throughout their adult lives. Their efforts had put them in a position to retire comfortably, giving them the opportunity to think about what they wanted their remaining years to look like. According to her account, financial stability had been a goal they worked toward rather than a benefit they simply expected to receive.
That position influenced how they viewed their savings and the responsibilities that came with retirement. They wanted to use the resources they had accumulated for their own lives instead of treating every remaining dollar as money reserved for their children. Their plans reflected a distinction between helping the next generation and accepting an open-ended obligation to finance its future.
Their Children Had Already Received Years of Financial Support
The mother explained that she and her husband had contributed substantially to raising their two children and preparing them for adulthood. They paid for a considerable portion of their children’s college expenses and continued covering health insurance and car insurance until the children moved out. They also provided ordinary necessities, including food, clothing, and housing, throughout their upbringing.
Their support extended beyond household bills and education. The parents drove the children to extracurricular activities that helped them pursue their interests, according to the letter. From the mother’s perspective, those years of practical and financial assistance were already a meaningful investment in her children’s futures.
The Parents Had Helped Their Children Enjoy Opportunities Growing Up
The letter also described experiences the couple had funded that went beyond everyday necessities. One example was a two-week trip to Europe that their children took as teenagers. It was part of the broader picture the mother presented of parents who had worked to give their children opportunities while they were growing up.
Those experiences helped explain why the couple did not see a future cash inheritance as the only measure of what they had provided. They had spent money on education, family life, and experiences before retirement, rather than postponing all financial support until after their deaths. The letter does not establish how the children themselves understood those contributions, but it makes clear that the parents considered their earlier support important.
Their Adult Children Appeared to Be Doing Well
The mother said both children were now grown and doing well, and the dinner conversation included their spouses. She did not describe either child as struggling financially or depending on the couple for ongoing assistance. That was an important part of her reasoning, because she believed her children did not appear to need money from a future estate.
Still, the parents could not know precisely what their children’s expectations were based on a joking exchange alone. A playful discussion about inheritance does not establish that someone is counting on a particular sum of money. The uncertainty was what prompted the mother to question whether an explicit conversation would prevent confusion later.
Their Paid-Off Home Was Part of Their Retirement Plan
The couple’s home was another important element in their plans for the future. The mother explained that the property was paid off, but they did not necessarily intend to preserve it for their children to inherit. Instead, they anticipated selling the house if they needed to pay for assisted living in their later years.
That possibility changed how the couple thought about the value they might eventually pass down. A home that could one day be sold to finance care was not simply an asset waiting to be transferred to the next generation. It was also a potential source of funds for the couple’s own housing and support needs.
They Wanted to Spend Their Savings on Their Own Future
The couple’s intention was not based on a firm prediction that they would have absolutely nothing left when they died. The mother said they hoped to enjoy comfortable and adventurous lives over the next 20 years, and they did not expect much money to remain if they followed that plan. They wanted their accumulated savings to support the retirement they had worked toward.
That decision created a question about expectations rather than a confirmed family disagreement. The letter did not describe a promise of inheritance that the couple had already made and then withdrawn. Instead, the parents were considering whether their children might benefit from hearing about their plans before an assumption about future wealth became a source of misunderstanding.
A Casual Conversation Left the Parents Wondering What to Do
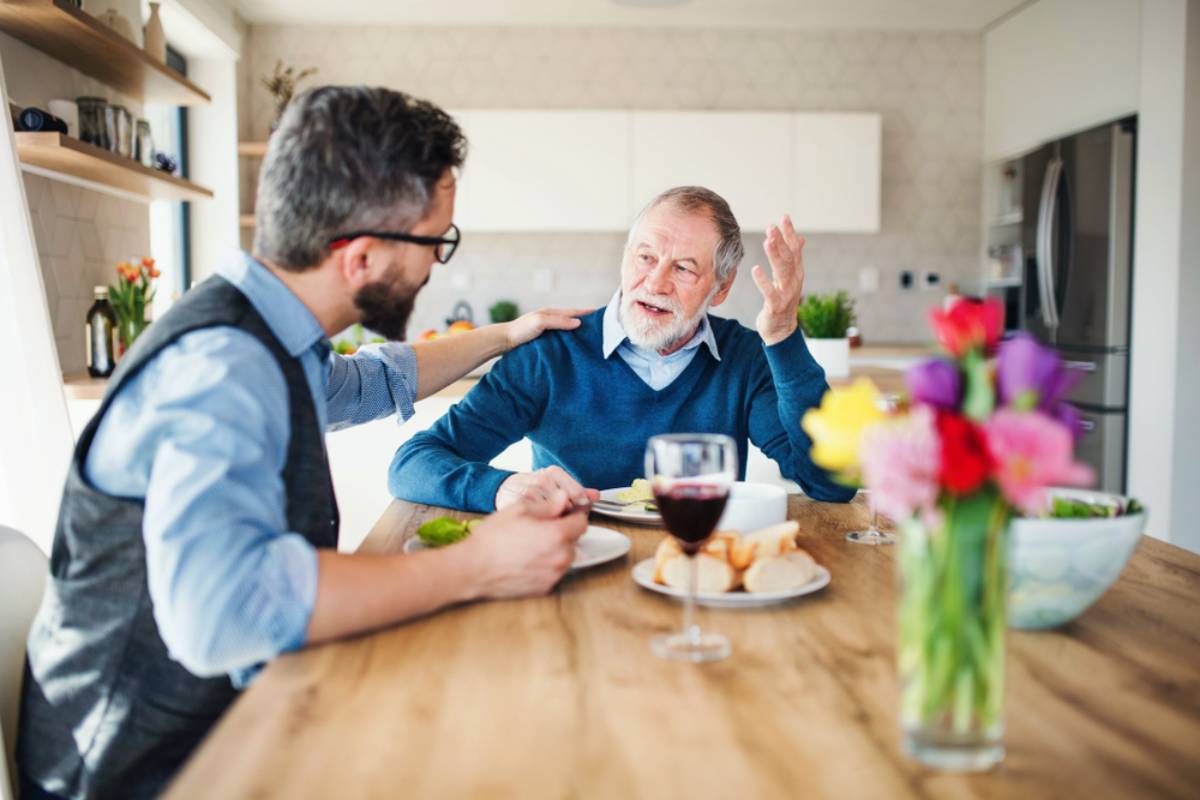
When the topic arose over dinner, the children joked about which sibling might be the favorite and who would inherit the family’s wealth. The parents understood the exchange as lighthearted and did not interrupt it with an explanation of their plans. Only later did they begin wondering whether their silence could leave an inaccurate impression.
The letter does not establish that either child expected a specific inheritance or that the family had argued about money. The concern belonged to the parents, who were reconsidering whether a joke deserved a more serious follow-up. That distinction matters because addressing a possible misunderstanding is different from resolving an actual dispute.
The Advice Was to Discuss Plans Rather Than Make a Big Announcement
In her response, columnist Olivia Christensen argued that the couple did not need to stage a dramatic announcement declaring that there would be no inheritance. She suggested bringing the children into the family’s planning instead of framing the conversation as a confession about how little money might remain. The purpose would be to help everyone understand what to expect, not to turn a routine financial discussion into a family confrontation.
The approach shifted attention from the amount of money the children might receive to the arrangements that would matter as their parents aged. It also allowed for uncertainty, since the couple could not predict every future expense or health development. Their plans could be discussed honestly without requiring them to guarantee a particular financial outcome decades in advance.
Rising Care Costs Can Change What Families Leave Behind
The couple’s concern about spending their savings has a wider context in the United States, where later-life care can substantially reduce the assets available to heirs. A Washington Post analysis of older Americans’ finances found that people who died between 2006 and 2022 spent a median of $19,179 out of pocket on care during their final decade of life. One in six people in the analysis spent more than $50,000.
The same reporting highlighted the potential cost of residential care, including assisted living and nursing-home services. Citing the 2025 CareScout Cost of Care Survey, it reported a national median annual cost of approximately $74,400 for assisted living and $129,575 for a private nursing-home room. Those figures do not predict what this particular couple will spend, but they illustrate why retirees may be reluctant to promise that today’s savings will become tomorrow’s inheritance.
Many Older Adults Want to Pass Down Wealth
The parents’ decision differs from a common aspiration among older Americans, although wanting to leave money and being able to do so are not the same thing. In a nationally representative survey described in AARP Research’s report on older adults and family finances, 83% of adults aged 50 and older said passing financial wealth and assets to family members was important or a priority. The findings indicate that leaving something for the next generation remains a meaningful goal for many people.
That broad preference does not mean every household has the resources to meet it. Families differ in their accumulated wealth, retirement savings, financial obligations, and access to professional planning support. The couple’s letter illustrates one possible difference in priorities: they wanted to enjoy the money they had saved rather than organize their retirement around preserving a legacy for their children.
Survey Data Also Shows a Gap Between Inheritance Expectations
A separate picture emerges from the Northwestern Mutual Planning & Progress Study 2025. According to the study’s findings on inheritance and financial planning, 30% of respondents in the Boomers+ category expected to leave an inheritance or financial gift or donation, while 9% expected to receive an inheritance themselves. Across all generations surveyed, 31% expected to leave an inheritance or financial gift or donation, and 20% expected to receive an inheritance.
These figures describe respondents’ expectations rather than guaranteeing what will happen to their estates. Savings, health needs, housing decisions, and other circumstances may change between the time a survey respondent makes a plan and the time an estate is eventually settled. The results nevertheless show why families should be careful about assuming that every older parent will leave a substantial sum behind.
Estate Planning Involves More Than the Final Amount
A central point in Christensen’s advice was that an estate still needs attention even when it is not expected to contain a large inheritance. Adult children may eventually need to help carry out their parents’ wishes, understand arrangements for care, and handle practical matters connected with the estate. Those responsibilities can exist regardless of whether much cash remains to distribute.
Planning can also involve decisions about who may help manage financial matters if a person becomes unable to do so independently. The Consumer Financial Protection Bureau explains in its guidance on financial powers of attorney that such a document can designate a trusted person to act on someone’s behalf when needed. The decision about whom to trust with that responsibility is separate from the question of who will ultimately inherit any remaining assets.
Family Possessions Can Carry Meaning Beyond Their Financial Value
Christensen also pointed out that family members may joke about inheritance while thinking about meaningful possessions rather than a large cash payment. In her own example, she described a collection of books belonging to her father and how she and her siblings jokingly argued about who might eventually receive them. The books were not presented as an especially valuable financial asset, but they held a place in the family’s shared life.
That example offered another way to think about what a person might leave behind. Belongings can matter to relatives because of their connection to a parent, grandparent, or shared family experience, even when their market value is modest. Thoughtfully deciding who should receive particular items can also reduce ambiguity about how possessions are to be distributed.
The Couple Could Focus on Expectations Without Promising an Inheritance
The practical question for the retired parents was how to explain their intentions while acknowledging that the future remained uncertain. They could make clear that their savings were intended to support their retirement and any care they might need, rather than suggesting that the children should expect a particular amount. That would communicate their priorities without claiming to know exactly what their eventual estate would contain.
A conversation could also cover the practical information that the children might need as their parents grew older. It would not require the couple to disclose every detail of their finances or commit to leaving nothing behind. The important distinction is between being transparent about plans and making a guarantee about a financial outcome that could change.
The Legacy They Built Was Already Visible in Their Family Life
The mother listed the ways she and her husband had supported their children because she was trying to understand what, if anything, they still owed them. Their account described years of raising two children, helping with education and expenses, and creating opportunities before retirement. Those contributions were tangible parts of the family’s history, regardless of what eventually remained in the estate.
Christensen’s response ultimately returned to the relationship described in the letter: parents and their grown children, with their spouses, sharing a meal and joking together about the future. The columnist treated that family connection as a meaningful legacy of its own, rather than measuring the parents’ success by the size of a future inheritance. Whether the couple chose to discuss their plans afterward was not established in the published account, but the advice made one point clear: an honest conversation about retirement and expectations does not have to begin with an apology for spending one’s own savings.