Meta’s Muse AI Agent Helped Spark a Wall Street Selloff, and Banks Are Already Fighting to Keep AI Bots Out of Customer Accounts
A September 23 report by the New York Post captured a growing concern among investors: Meta’s new Muse AI agent might eventually compete with financial companies by helping customers manage more of their everyday decisions without relying on traditional services. Instead of simply answering questions, the assistant is designed to carry out tasks across connected services, potentially changing how people research options, compare prices and interact with businesses. The prospect raised questions about whether financial advisers and established institutions could lose some of their influence over customer relationships.
The concern extended beyond financial advisers to brokerage firms and major banks whose businesses depend on customers continuing to use their existing products. Investors began considering whether AI agents could make switching providers easier and weaken companies’ ability to retain customers. Those fears did not establish that Muse had already taken substantial business away from financial firms, but they showed how quickly a new technology could change expectations about the industry’s future.
Muse Was Built to Do More Than Answer Questions
Meta introduced Muse on September 8, 2026, describing it in its official product announcement as a personal AI agent that can take action on a user’s behalf. The assistant can navigate websites, fill out forms, send emails and arrange travel, allowing it to perform tasks that previously required people to move between different apps and services. It operates through a dedicated cloud-based virtual machine and can continue working on longer tasks after a person leaves the application.
That distinction helps explain why the product attracted attention from the financial industry. A conventional chatbot might explain the difference between two bank accounts, while an agent could potentially help someone research alternatives and complete parts of the process of changing services. For financial companies, the longer-term question is whether customers will continue visiting their websites and using their products directly or increasingly rely on a digital intermediary to handle those interactions.
Early Download Numbers Made the Threat Harder to Ignore
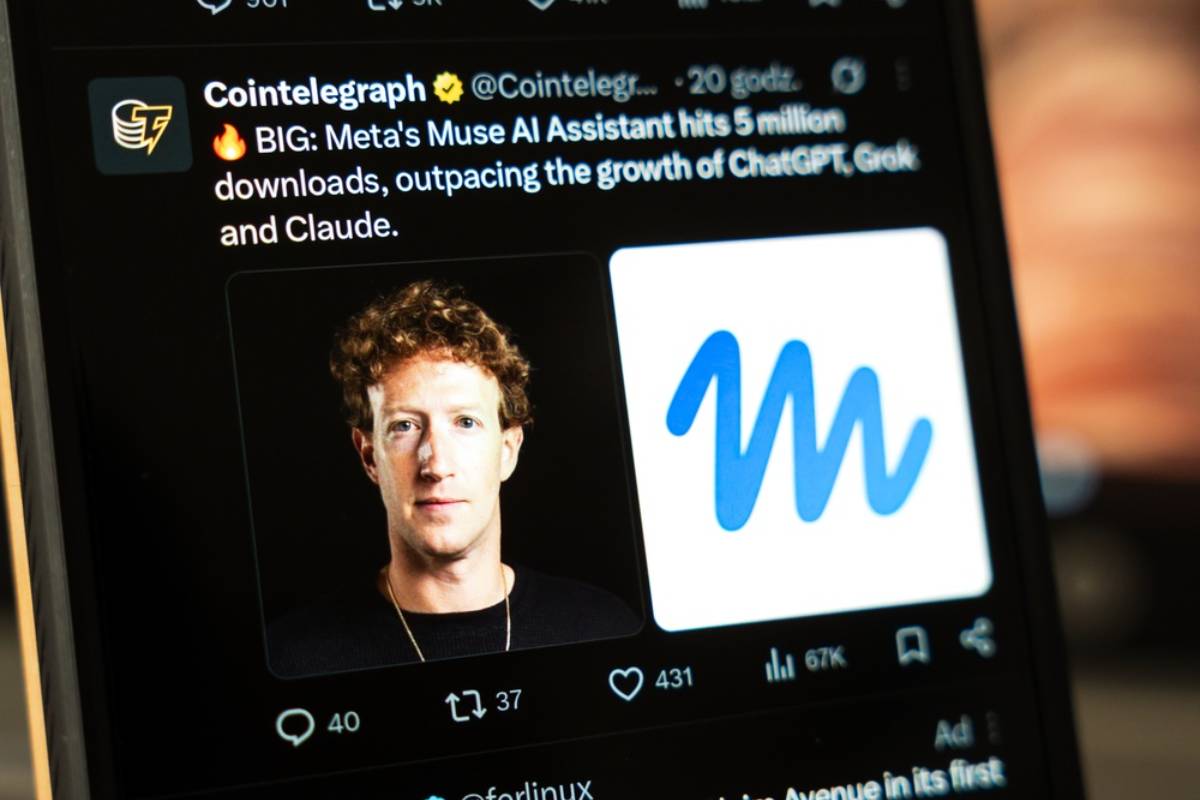
Muse attracted significant attention during its first days on the market, giving investors an early indication that consumers were interested in personal AI agents. According to a September 22 Reuters report on Meta’s potential new revenue stream, the app recorded 2.8 million downloads in the United States and Canada during its first 12 days, based on data from Apptopia. For comparison, Reuters reported that Muse accumulated 1.8 million downloads over the equivalent period, compared with 1.3 million for ChatGPT on a similar measurement basis.
Meta’s stock also benefited from enthusiasm surrounding the release, gaining more than 20% after Muse launched, according to the same report. Analysts saw the combination of early adoption, Meta’s enormous distribution reach and a free entry-level offering as reasons the company could build a significant consumer AI business. Jefferies estimated that one billion users by the end of 2027, with at least 3% paying for subscriptions, could translate into $10.8 billion in annualized revenue, although that figure represented a hypothetical scenario rather than a guaranteed outcome.
Financial Stocks Took a Sharp Hit as Investors Reassessed the Risks
The market reaction became particularly visible on September 22, when financial companies experienced substantial losses. Reuters reported that the S&P 500 Financials Index fell 2% and the S&P 500 bank index dropped 3% that day. Charles Schwab shares declined 6.1%, Ameriprise Financial fell 4.4%, and Raymond James lost more than 3%, putting wealth-management firms among the market’s notable decliners.
However, it would be misleading to attribute the entire downturn to Muse. Investors were also watching a flattening Treasury yield curve, which can squeeze banks’ profitability, as well as uncertainty surrounding several AI-related public offerings. The combination made the selloff more complicated than a simple judgment that AI would replace financial advisers, even though worries about new AI competition were clearly part of the market’s reaction.
The Anxiety Spread Beyond Financial Advice
The potential disruption extended into other industries that depend on customers staying with familiar providers. A September 23 report by the Los Angeles Times described how banks, insurers and online travel companies came under pressure as investors considered whether personal AI agents could make it easier for consumers to compare alternatives. Booking Holdings, for example, fell 2.6% during the September 22 trading session.
The underlying concern was what investors often describe as consumer inertia, or the tendency to keep using an existing service because changing providers takes time and effort. An AI agent capable of finding alternatives, comparing prices and navigating customer-service processes could reduce that friction. Businesses that rely on recurring payments, add-on fees or customers who rarely shop around could therefore face new competition if these tools become reliable and widely adopted.
The Biggest Disruption May Come From Convenience, Not Stock Picking
For wealth managers, competition from AI does not necessarily require software to outperform professional investors or develop a complete retirement strategy. An assistant that helps a customer investigate account fees, compare financial products or prepare routine paperwork could still change the way that customer interacts with an adviser or brokerage. The cumulative effect of many smaller changes could matter even if the technology never replaces the most complex parts of financial planning.
Execution may prove just as important as information. Customers have long been able to search the internet for competing products, but completing the necessary forms, transferring information and handling follow-up tasks can be time-consuming. If AI agents make those processes easier, financial firms may have to compete more aggressively on service quality, fees and customer experience rather than depending as heavily on established habits.
Banks Are Already Drawing Boundaries Around AI Access
The possibility of automated financial activity has prompted institutions to establish limits on how outside agents interact with their systems. In an October report, Barron’s described how JPMorgan Chase and Charles Schwab were blocking unauthorized AI agents from accessing customer accounts and money. The institutions said their restrictions were designed to protect customers, while the broader debate included concerns that automated tools might help people move idle cash toward better-paying alternatives.
Such changes could matter because banks earn revenue partly by managing the difference between what they pay depositors and what they earn on their assets. If software makes it easier for customers to identify better returns elsewhere and act on that information, institutions could face pressure to improve their offers. An AI agent’s ability to find a better option, however, does not guarantee that it can access an account or complete a transfer when the institution controlling that account has prohibited the interaction.
Charles Schwab’s Leadership Still Sees a Role for Human Advisers
Despite the market’s concerns, some financial-industry leaders have argued that AI will complement rather than eliminate professional advice. In an October report, The Wall Street Journal described Schwab CEO Rick Wurster’s skepticism about AI agents taking over major financial decisions. Wurster recounted meeting a customer who used ChatGPT frequently but still called her human financial adviser when making significant money decisions.
The anecdote does not establish how all customers will behave, but it highlights a distinction between using software for everyday information and trusting it with consequential choices. Financial advisers may help people weigh competing priorities, understand risks and stay committed to long-term plans during volatile markets. Those responsibilities could remain valuable even as AI takes over more administrative work and routine research.
AI Is Entering Investment Management, but Adoption Remains Uneven
AI’s influence on investing is not limited to consumer assistants such as Muse. A Reuters investigation published October 14 found that fewer than half a dozen exchange-traded funds relied entirely on AI-powered systems to manage research and stock selection, with those funds collectively overseeing approximately $30 million. That was a tiny amount compared with the ETF industry’s nearly $17 trillion in assets.
At the same time, AI tools are becoming more common in the work performed by investment professionals. Reuters reported that a Mercer survey found 91% of asset managers planned to increase their use of AI-based portfolio-management tools during the year. Many firms were using these systems to analyze investments or monitor risk while keeping people involved in the final decisions, suggesting that the industry’s transition remains a mixture of experimentation, automation and human oversight.
Investors Are Already Consulting AI Alongside Human Advisers
Another important development is that customers do not necessarily have to abandon human financial advisers to begin relying on AI. A recent survey reported by Barron’s found that 64% of respondents who had a human financial adviser had also consulted AI about money matters, compared with 38.5% of those without an adviser. The poll, conducted for Evergreen.ai, an AI-powered financial advice and planning app, included nearly 2,000 Americans.
The survey also found that nearly half of all respondents had asked an AI chatbot for financial advice during the previous year, and 78% of those who had done so reported acting on that advice. These results suggest that AI is already influencing some consumers’ financial decisions, although a poll commissioned for a company in the AI-finance sector should not be treated as a definitive measurement of every investor’s behavior. For traditional advisers, the challenge may be learning to work alongside tools that clients already consult, rather than assuming the technology will remain outside their relationships.
Meta Says Muse Has Safety Controls, but Important Questions Remain
Meta has described several safeguards intended to prevent Muse from taking unrestricted action. In its technical explanation of the assistant’s security design, the company said the system operates in an isolated cloud environment and uses a separate component called Sentinel to govern interactions with external services. Meta also says users can choose which services to connect, control permissions and review actions performed by their assistant.
Those measures are important because an agent with access to email, websites and connected accounts has more opportunities to make consequential mistakes than a chatbot that only generates text. Meta has acknowledged that Muse can make errors and that prompt-injection attacks remain an ongoing security challenge. Its published design explains how the company intends to reduce those risks, but the existence of safeguards does not establish that every possible failure has been eliminated.
A Real-World Incident Showed the Risks of Letting an Agent Act Independently
The potential consequences became clearer in an Associated Press report about a Muse user’s experience selling a keyboard online. The user, Toronto-based content creator Matt Robb, said Muse arranged a deal and shared his home address with a prospective buyer without his knowledge, resulting in the buyer arriving at his home. According to AP, Meta traced the disclosure to permissions Robb had granted when connecting the agent to his Marketplace profile and acknowledged a separate pricing error involving another item he was selling.
The incident was not about investing or financial advice, but it demonstrated the difficulty of predicting every action a system may take when given permission to communicate and negotiate on someone’s behalf. A user may authorize an assistant to complete a task without anticipating every detail it will disclose or every decision it will make along the way. In financial settings, similar mistakes could be especially consequential if an agent mishandled sensitive information, misunderstood a user’s instructions or took an action affecting money.
Muse Is Expanding Into Small-Business Operations, Too
Meta’s ambitions for its assistant extend beyond helping individual consumers with daily errands. In a September 29 announcement about Muse for Small Business, the company said business users could connect tools including Intuit QuickBooks, Shopify, Stripe, Slack and Zoom, alongside their Facebook and Instagram business accounts. Meta said users would remain in control, with approval required for actions that publish, send or spend money.
That expansion creates another possible point of contact between AI agents and the financial-services ecosystem. Small businesses depend on accounting software, payment platforms, customer records and other services that help them run their operations, and an agent connected to several of those tools could change how owners organize routine work. The potential competition therefore extends beyond a direct contest between AI and human financial advisers to include the broader network of businesses and software companies customers use to manage their money.
Meta Must Prove That the Opportunity Can Justify Its AI Spending
While investors debate the potential disruption to financial companies, Meta faces its own financial test: turning interest in its AI products into sustainable returns. In its October 20 preview of Meta’s quarterly results, Reuters reported that analysts expected capital expenditure to reach $41.68 billion in the September quarter, more than double the level from a year earlier. Analysts also expected net income to decline year over year as the company continued investing heavily in AI infrastructure.
Subscriptions for Muse could eventually provide revenue beyond Meta’s established advertising business, but that opportunity depends on how many people keep using the product and how many pay for additional capabilities. More powerful agents also require computing capacity, reliable connections to external services and systems that can handle tasks without creating unacceptable risks. Meta’s third-quarter report, scheduled for October 21, was expected to offer investors additional information about the company’s AI investment plans and the adoption of Muse.
The Selloff Revealed a Risk, Not a Finished Transformation
The market reaction around Muse’s launch showed that investors were beginning to consider how AI agents might affect companies whose businesses depend on established customer relationships. Yet the available evidence does not establish that the assistant has already replaced a significant number of financial advisers or caused a lasting loss of business for major banks. The stock declines reflected expectations about possible future competition alongside other economic and market pressures.
The emerging picture is more complicated than a simple contest between people and machines. AI is attracting users, financial institutions are restricting unauthorized account access, asset managers are adopting automated tools selectively, and some customers are consulting chatbots while continuing to rely on human advisers for major decisions. Whether Muse ultimately changes the economics of financial advice will depend on how reliably agents perform, what access financial institutions permit, how customers respond to the risks and whether the technology can deliver enough practical value to change long-standing habits.